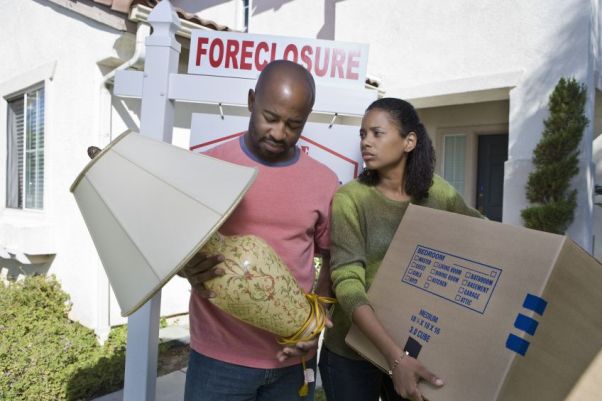
 As headlines trumpet a full recovery in the housing market, a new report finds that this wave of prosperity has missed Black and brown communities.
The report, “Underwater America,” released this month by the Haas Institute for a Fair and Inclusive Society at UC Berkeley, details the ongoing mortgage crisis in pockets around the country. In breaking down the data by metropolitan area, city, and ZIP code, researchers find that still-distressed areas are predominantly communities of color.
“While some communities across the country have benefited from rising home prices, this upward trend is expected to slow down dramatically in 2014, which means the hot spots that have been left behind by the recovery are not likely to see their fortunes substantially improve anytime soon,” the report reads.
In 71 of the 100 hardest-hit cities, Blacks and Latinos make up at least 40 percent of the population. (The five hardest-hit large cities are: Hartford, Connecticut; Newark, Elizabeth, and Patterson in New Jersey; and Detroit). According to the report, in these 100 cities, home prices are still up to 57 percent lower than their peak offer. These “underwater” homeowners are up to 200 percent more likely to lose their homes to foreclosure, because they owe more on their mortgages than their homes are worth.
Since 2008, nearly 5 million families have already met this fate.
“If nothing happens, we’ll see continued foreclosures and the cities themselves will be hit, because it erodes the tax base of a city,” says john a. powell, director of the Haas Institute (he prefers to keep his name lower-cased). “It’s a snowball effect. We see it in Detroit, in Flint…a lot of cities are struggling, but they always say these cities are bad in some way. They fail to look at how the banks, the federal government, and the city officials should shoulder blame.”
These communities are all epicenters of the subprime loan industry, and are full of victims of the predatory lending practices that caused the Great Recession.
Homeownership has long been a steady road to the middle-class American Dream for Black families—the report points out that 92 percent of Black net worth is wrapped up in homes. The subprime loan crisis largely obliterated that asset; between 2005 and 2009, African-Americans lost more than half of all household wealth (Latinos lost 66 percent). Today, African-American household net worth is less than 5 percent of its white counterparts.
“It actually puts us into the negative with wealth building,“ says powell. “If [the nation] continues this way…the long term effect will be extreme racial and economic inequality.”
While there have been many federal interventions to cauterize the problem—namely, Federal Reserve aid programs and class-action lawsuit settlements from financiers such as JPMorgan Chase—powell says they are not enough. The report explains that without forcing loan providers to refinance mortgages, or reduce the principal balance of underwater homes to their current market rates, these interventions won’t turn the tide for the bulk of struggling homeowners.
“The future depends largely on those policy decisions that are made, and sometimes not made,” the report explains. “But there are steps that communities can take, preferably in partnership with private and nonprofit organizations and government agencies at all levels, to ameliorate these costs.”
Some citizens and cities are taking such steps and bailing themselves out with innovative solutions. Statesmen and community organizations in Richmond, Calif., for example, are using eminent domain to buy mortgages on underwater homes and refinance the loans to help families avoid foreclosure. Powell encourages underwater homeowners, concerned citizens, and interested officials to band together on an interstate level to take similar action, and to lobby their local, state, and national lawmakers.
“When banks started to fail, the government didn’t say ‘OK each bank, figure out your own problems.’ We funded them with taxpayer money, and after we bailed them out they gave each other raises,’” Powell says. “We don’t see the same collective response to people in communities of color. The solution can’t be at an individual level. It’s a structural problem and needs to have a structural solution.”


